By Kehinde Ibrahim
THE Central Bank of Nigeria (CBN) has said the success of the banking sector’s recapitalisation programme will ultimately be measured by the ability of stronger banks to expand productive lending, improve financial services and strengthen the resilience of the Nigerian economy.
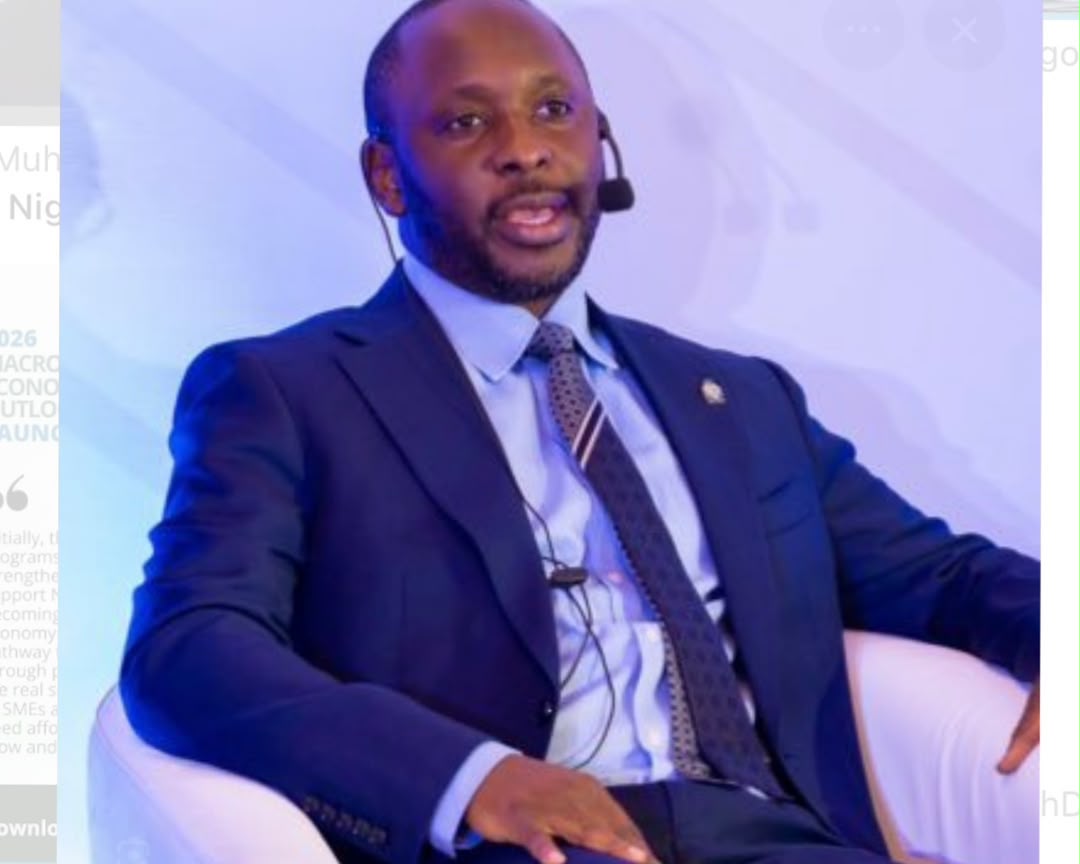
The Deputy Governor, Corporate Services, CBN, Dr. Muhammad Sani Abdullahi, stated this on Tuesday at the 38th Seminar for Finance Correspondents and Business Editors organised by the Finance Correspondents Association of Nigeria (FICAN).
Speaking on the theme, “Towards a Robust and Resilient Financial System in the Post-Banking Sector Recapitalisation Era,” Abdullahi said the recapitalisation programme was part of a broader reform agenda aimed at restoring macroeconomic stability, rebuilding confidence and strengthening the capacity of the financial system to support economic growth.
He said the reforms initiated over the past three years were undertaken against the backdrop of significant pressures in the foreign exchange market, elevated liquidity, weak capital inflows and uncertainty affecting businesses and investors.
According to him, by 2023, Nigeria’s foreign exchange market was heavily administered and fragmented, with multiple trading windows operating alongside a large parallel market. He said the gap between official and parallel market rates averaged more than 60 per cent in 2022 and exceeded 100 per cent at certain points towards the end of the year.
Abdullahi noted that the World Bank had estimated that the implicit subsidy associated with the exchange-rate arrangement cost the country about three per cent of Gross Domestic Product in 2022.
He added that pressure on the external sector was compounded by weak net usable reserves, noting that after accounting for identified short-term obligations, net usable reserves stood at $859 million in the second quarter of 2023.
The CBN deputy governor also disclosed that outstanding foreign exchange forward claims had exceeded $7 billion at the time, creating additional uncertainty for businesses and investors.
On domestic monetary conditions, he said Ways and Means financing had risen to about N26.6 trillion by 2023, while legacy development finance exposures exceeded N10 trillion.
According to him, the resulting liquidity pressures made inflation more difficult to contain and weakened the transmission of monetary policy, while reduced capital inflows and uncertainty over access to foreign exchange further constrained businesses.
He explained that the CBN therefore adopted a coordinated approach to address the challenges rather than tackling them independently.
“The foreign exchange market needed clearer prices and more reliable trading arrangements, but those changes would be difficult to sustain without tighter control of liquidity. We also needed stronger banks capable of operating through the adjustment,” he said.
Abdullahi recalled that the CBN began the foreign exchange reforms in June 2023 by consolidating existing windows and moving towards a willing-buyer, willing-seller framework.
He said the Bank subsequently removed restrictions that had prevented 43 categories of imports from accessing the official foreign exchange market and reviewed outstanding forward claims, with valid claims settled to reduce uncertainty for businesses and investors.
The CBN also strengthened foreign exchange trading and reporting rules, introduced the Electronic Foreign Exchange Matching System for interbank transactions and established the Nigerian FX Code to promote greater transparency and improved market conduct.
At the same time, the apex bank tightened monetary policy, strengthened liquidity management and commenced the gradual winding down of development finance interventions.
Abdullahi said the banking sector recapitalisation programme, announced in March 2024, complemented the reforms by requiring banks to raise capital appropriate to their respective licences within two years.
He disclosed that by the end of the programme, 33 banks had met the revised minimum capital requirements and collectively raised N4.65 trillion.
He said the stronger capital base would enhance the capacity of banks to finance infrastructure, industrial expansion and international trade, while enabling them to compete more effectively in regional and global markets.
According to him, stronger capital buffers would also provide banks with greater capacity to absorb losses during periods of economic stress and sustain investments in innovation and digital transformation.
The deputy governor said the reforms had also contributed to improved conditions in the foreign exchange market.
He disclosed that the average gap between official and parallel market exchange rates had fallen from 68.2 per cent between January and May 2023 to less than two per cent.
He said the development had provided businesses with a more reliable basis for pricing, investment and financial planning.
Abdullahi further disclosed that foreign exchange inflows were increasingly being driven by autonomous sources. Of the $10.82 billion in total inflows recorded in July 2026, he said $7.33 billion, representing nearly 68 per cent, came from autonomous sources.
He added that remittances through International Money Transfer Operators reached $950 million during the month, while net foreign portfolio inflows totalled $6.31 billion between January and August 2026.
The deputy governor acknowledged that portfolio flows could reverse, but said the broader improvement in foreign exchange supply had reduced the market’s reliance on direct CBN intervention.
He also disclosed that the country’s gross external reserves stood at $55.60 billion as of September 11, 2026, while the end-August reserve position provided 11.3 months of import cover.
On inflation and economic growth, Abdullahi said headline inflation, which rose to 34.8 per cent in December 2024 during the initial adjustment period, had moderated to 15.43 per cent by July 2026.
He added that the economy recorded real GDP growth of 4.43 per cent in the second quarter of 2026, driven largely by non-oil activities.
However, he cautioned that the improvements should not be interpreted as an end to economic pressures facing households and businesses.
“These outcomes reflect several influences, including monetary policy, oil receipts, remittances and global financial conditions. They show progress, but they do not mean the pressure on households and businesses has ended,” he said.
Abdullahi stressed that the next phase of the reform programme would require stronger supervision, sound corporate governance and improved risk management across the banking sector.
He said banks must go beyond maintaining adequate capital by ensuring that boards and management teams maintain effective internal controls, identify risks early and lend to viable projects.
He identified market, liquidity and operational risks, cybersecurity, third-party dependencies and climate-related financial risks as areas requiring increased attention from financial institutions.
The CBN, he said, would continue to focus on governance, asset quality, liquidity and large exposures, while requiring banks to strengthen customer data protection, payment-system reliability and business continuity arrangements.
He said the apex bank would also maintain its emphasis on risk-based supervision, macroprudential surveillance and enhanced stress testing.
According to him, financial sector coordination, consumer protection, fintech regulation, responsible innovation, crisis preparedness and resolution planning would remain key components of the regulatory framework.
Abdullahi said the benefits of banking recapitalisation should ultimately extend beyond stronger balance sheets to agriculture, manufacturing, services, infrastructure, small businesses and households.
He stressed that banks should provide financing that reflects the cash flows and investment horizons of businesses, while expanding access to appropriate and dependable financial products.
He also called for greater financial inclusion, particularly among rural communities, women and young entrepreneurs, noting that consumer protection and access to trusted financial services were essential components of a resilient financial system.
The deputy governor urged businesses to strengthen their corporate transparency, governance and sustainability practices to improve their ability to access financing.
He said stronger banks could provide financing for investments in technology, energy, transportation, power, agriculture, manufacturing and other productive sectors, but businesses must also improve productivity and adopt long-term planning.
Abdullahi further highlighted the role of the financial press in monitoring the impact of the reforms.
He said accurate and objective reporting would help the public understand developments in the financial sector, promote investor education and support informed public debate.
He commended FICAN for its commitment to professionalism and ethical journalism, urging finance correspondents and business editors to continue providing analytical and fact-based coverage of the financial system.
He said the media, regulators, financial institutions, businesses, investors and the public all had responsibilities in building a financial system capable of withstanding shocks, supporting innovation and broadening economic opportunities.
“Three years into this reform effort, the foundations of monetary and financial stability are stronger. Sustaining that progress will require disciplined supervision, responsible banking and continued attention to the people and businesses the financial system serves,” Abdullahi said.
He added that with prudence, transparency and collaboration, stronger banks and deeper financial markets could contribute significantly to Nigeria’s long-term development ambitions.

